
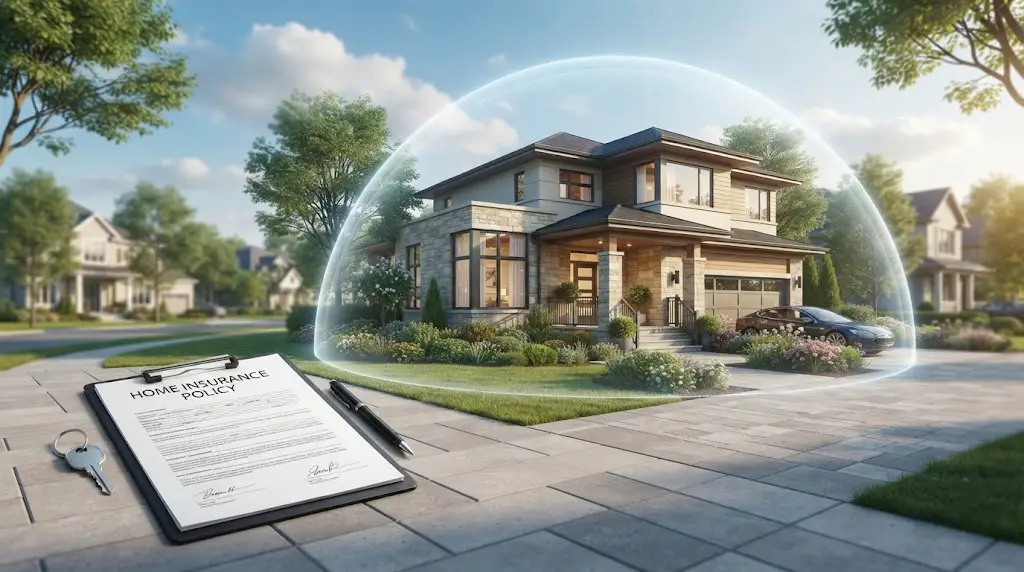
Homeowners insurance generally helps protect the structure of a residence, personal belongings, and the policyholder’s liability for certain covered incidents. The exact protection depends on the policy, exclusions, limits, endorsements, and applicable state requirements. For broader insurance-related information, readers can also explore international health insurance and other insurance topics available on PostingNest.
What Is Astera Homes Insurance?
The phrase Astera Homes Insurance can be used by people researching insurance protection connected with a home or residential property. Before purchasing any policy, it is important to identify the actual insurer, understand the policy documents, and confirm which risks and property features are covered.
Homeowners insurance commonly combines several forms of protection. Depending on the policy, this can include dwelling coverage, coverage for other structures, personal property protection, loss-of-use coverage, personal liability, and medical payments coverage.
Because insurance contracts differ between companies and jurisdictions, homeowners should never assume that a particular loss is covered simply because it is commonly associated with homeowners insurance.
Why Home Insurance Matters for Property Owners
A home can represent one of the largest assets a person owns. Damage from a covered event can create substantial repair or rebuilding costs, while damage to furniture, electronics, clothing, appliances, and other belongings can create additional financial pressure.
Homeowners insurance can provide financial protection against covered losses and may also provide liability protection when the policyholder is legally responsible for certain injuries or property damage involving others.
Mortgage lenders commonly require homeowners insurance because they have a financial interest in the property. This makes understanding your coverage important not only for protecting your investment but also for maintaining the insurance requirements associated with a mortgage.
For another perspective on protecting and maintaining residential property, readers may also find home exterior cleaning services useful when considering broader property maintenance.
Key Types of Coverage to Understand
1. Dwelling Coverage
Dwelling coverage generally applies to the main structure of an insured home and certain attached components. The appropriate limit should be based on the estimated cost to rebuild rather than simply the property’s market value.
2. Other Structures
Detached garages, sheds, fences, and similar structures may fall under an other-structures portion of a homeowners policy, subject to its limits and covered causes of loss.
3. Personal Property
Personal property coverage can help protect belongings such as furniture, clothing, electronics, and other household possessions when they are damaged or lost through a covered event. Certain valuable categories may have special limits, making a detailed home inventory particularly useful.
Homeowners interested in organizing and improving their living environment can also explore Montana lifestyles and dinnerware as part of the wider home-and-lifestyle content available on the site.
4. Loss of Use
If a covered loss makes a home temporarily uninhabitable, a policy may provide additional living expense or loss-of-use coverage, subject to the policy’s terms and limits.
5. Personal Liability
Liability coverage can help protect a homeowner against certain covered claims involving bodily injury or property damage for which the insured is legally responsible.
6. Medical Payments
Some homeowners policies include medical payments coverage for qualifying injuries involving people who are not insured members of the household. The specific conditions and limits are determined by the policy.
Replacement Cost vs. Actual Cash Value
One of the most important concepts when reviewing homeowners insurance is the difference between replacement cost and actual cash value.
Replacement cost coverage generally considers what it would cost to repair or replace damaged property with materials of similar kind and quality, without deducting depreciation where the policy provides replacement-cost protection. Actual cash value, by contrast, generally takes depreciation into account.
For example, an older roof may have a much lower actual cash value than the cost of installing a new roof. Understanding which valuation method applies can therefore make a significant difference when a claim is settled.
NAIC consumer guidance recommends understanding these differences before purchasing or renewing a homeowners policy.
How Deductibles Affect Your Policy
A deductible is the amount the policyholder is responsible for paying toward a covered claim before the insurer pays the remaining eligible amount, subject to the policy limit and other conditions.
Policies with higher deductibles may have lower premiums, while lower deductibles can increase premium costs. The important consideration is whether you could comfortably afford the deductible following a significant covered loss.
Some policies can also contain percentage-based deductibles for particular risks. Homeowners should therefore read the declarations page and policy documents carefully rather than assuming every deductible is a fixed dollar amount.
For more information about deductibles and insurance protection, readers can also explore Auros Insurance Company and insurance solutions and financial protection.
What Can Influence Home Insurance Costs?
The price of homeowners insurance can vary considerably from one property and policy to another. Insurers may consider factors associated with the property, location, construction characteristics, coverage limits, deductible, claims history, and selected optional protections.
The value used for rebuilding purposes is also important. A property’s market price includes factors such as land value and local real-estate conditions, while dwelling coverage is intended to address the cost of rebuilding the insured structure.
Homeowners should also remember that premium comparisons are meaningful only when the underlying coverage is comparable. A cheaper policy with lower limits or broader exclusions is not necessarily equivalent to a more comprehensive policy.
Maintaining the physical property can also be part of responsible homeownership. For example, readers can learn more about mobile home leveling and structural stability or review information about home and garden improvements.
How to Evaluate an Astera Homes Insurance Policy
If you are researching an insurance product associated with the Astera Homes name, start by verifying the insurer and reviewing the actual policy documentation. Do not rely only on a marketing description or a headline.
- Confirm the legal name of the insurance company.
- Check whether the company is authorized to sell insurance in your jurisdiction.
- Review the dwelling coverage limit.
- Check personal property and other-structures limits.
- Understand personal liability coverage.
- Review every deductible that could apply.
- Read exclusions and limitations carefully.
- Determine whether property is covered at replacement cost or actual cash value.
- Ask whether flood, earthquake, sewer backup, or other specialized risks require separate coverage or an endorsement.
- Keep copies of the declarations page and policy documents.
NAIC guidance similarly recommends comparing insurers, understanding coverage, checking deductibles, and making sure the policy provides the protection you actually need.
Creating a Home Inventory Before You Need It
A home inventory can make the claims process easier because it creates a record of the belongings inside the property. Homeowners can document major possessions using photographs, receipts, model numbers, purchase records, and other identifying information.
High-value jewelry, artwork, collectibles, electronics, and other special possessions may have specific limits under a standard policy. Depending on the policy, additional coverage or endorsements may be available.
For readers interested in property-related lifestyle topics, Shine Lifestyle Shop provides another example of the wider lifestyle content available on PostingNest, while home cleaning services highlight another practical aspect of property care.
Common Questions About Astera Homes Insurance
Is Astera Homes Insurance a specific insurance company?
The name alone should not be treated as proof of a particular insurance carrier. Before purchasing coverage, verify the insurer’s legal identity, licensing status, policy form, and official documentation.
Does homeowners insurance cover everything inside a house?
No. Coverage depends on the policy, covered perils, limits, exclusions, deductibles, and endorsements. Certain valuable possessions or specific risks may require additional protection.
Does homeowners insurance cover flooding?
Standard homeowners insurance commonly does not provide coverage for flood damage. Separate flood insurance may be available depending on the homeowner’s location and circumstances. Always check the policy and local insurance requirements.
What is the difference between a deductible and a premium?
The premium is the amount paid for the insurance policy, while the deductible is the portion of a covered loss the policyholder is responsible for paying before the insurer contributes according to the policy.
Should homeowners review their insurance every year?
Yes. A periodic review can help identify changes in rebuilding costs, renovations, household possessions, deductible preferences, and other circumstances that could affect the appropriate amount of coverage.
Final Thoughts on Astera Homes Insurance
Choosing home insurance should be based on the actual protection provided by the policy rather than the name attached to it. Anyone researching Astera Homes Insurance should verify the insurer, compare coverage limits, understand deductibles, review exclusions, and determine whether replacement-cost or actual-cash-value protection applies.
A well-organized home inventory and regular policy review can also help homeowners stay prepared as their property and circumstances change. For additional insurance-related reading, Max Brown Insurance and RXGRP information on an insurance card offer related topics.
For broader property and lifestyle coverage, explore PostingNest, where readers can find additional guides across insurance, home, lifestyle, health, travel, and other subjects.